Scrape London Hotel Chain Location Data 2026: 5,822 New Rooms — Marriott, Hilton, IHG Supply Map
This report analyzes leading hotel chains in London, their location-wise distribution, hotel room supply, occupancy trends, and data-driven expansion opportunities for 2026.
Introduction
London remains one of the world's most competitive hospitality markets, supported by international tourism, corporate travel, major events, business districts, cultural attractions, and strong transport connectivity. To understand this evolving market, hospitality companies increasingly Scrape London Hotel Chain Location Data 2026 to monitor hotel openings, closures, brand penetration, room supply, pricing, and geographic expansion.
London's branded hotel ecosystem spans luxury, upscale, mid-scale, economy, lifestyle, and extended-stay properties. Current hotel directories show extensive concentration across Westminster, Mayfair, Kensington, Paddington, City of London, Canary Wharf, South Bank, Stratford, and other major districts. Marriott's London portfolio currently displays 74 hotels, while Visit London identifies around 49 Hilton-branded properties including airport locations. Accor lists more than 45 hotels across its London portfolio.
The market is also experiencing continued brand expansion. In May 2026, IHG announced Canary Riverside Plaza, Vignette Collection by IHG, marking the brand's London debut.
London's hotel performance provides an important backdrop for expansion planning. Full-year 2025 hotel occupancy reached 82.5%, up 1.2 percentage points year over year, according to Knight Frank.
400+
Hotel Chain
Properties
Monitored
25+
Major Hotel
Brands
30+
London Districts
& Travel Corridors
Covered
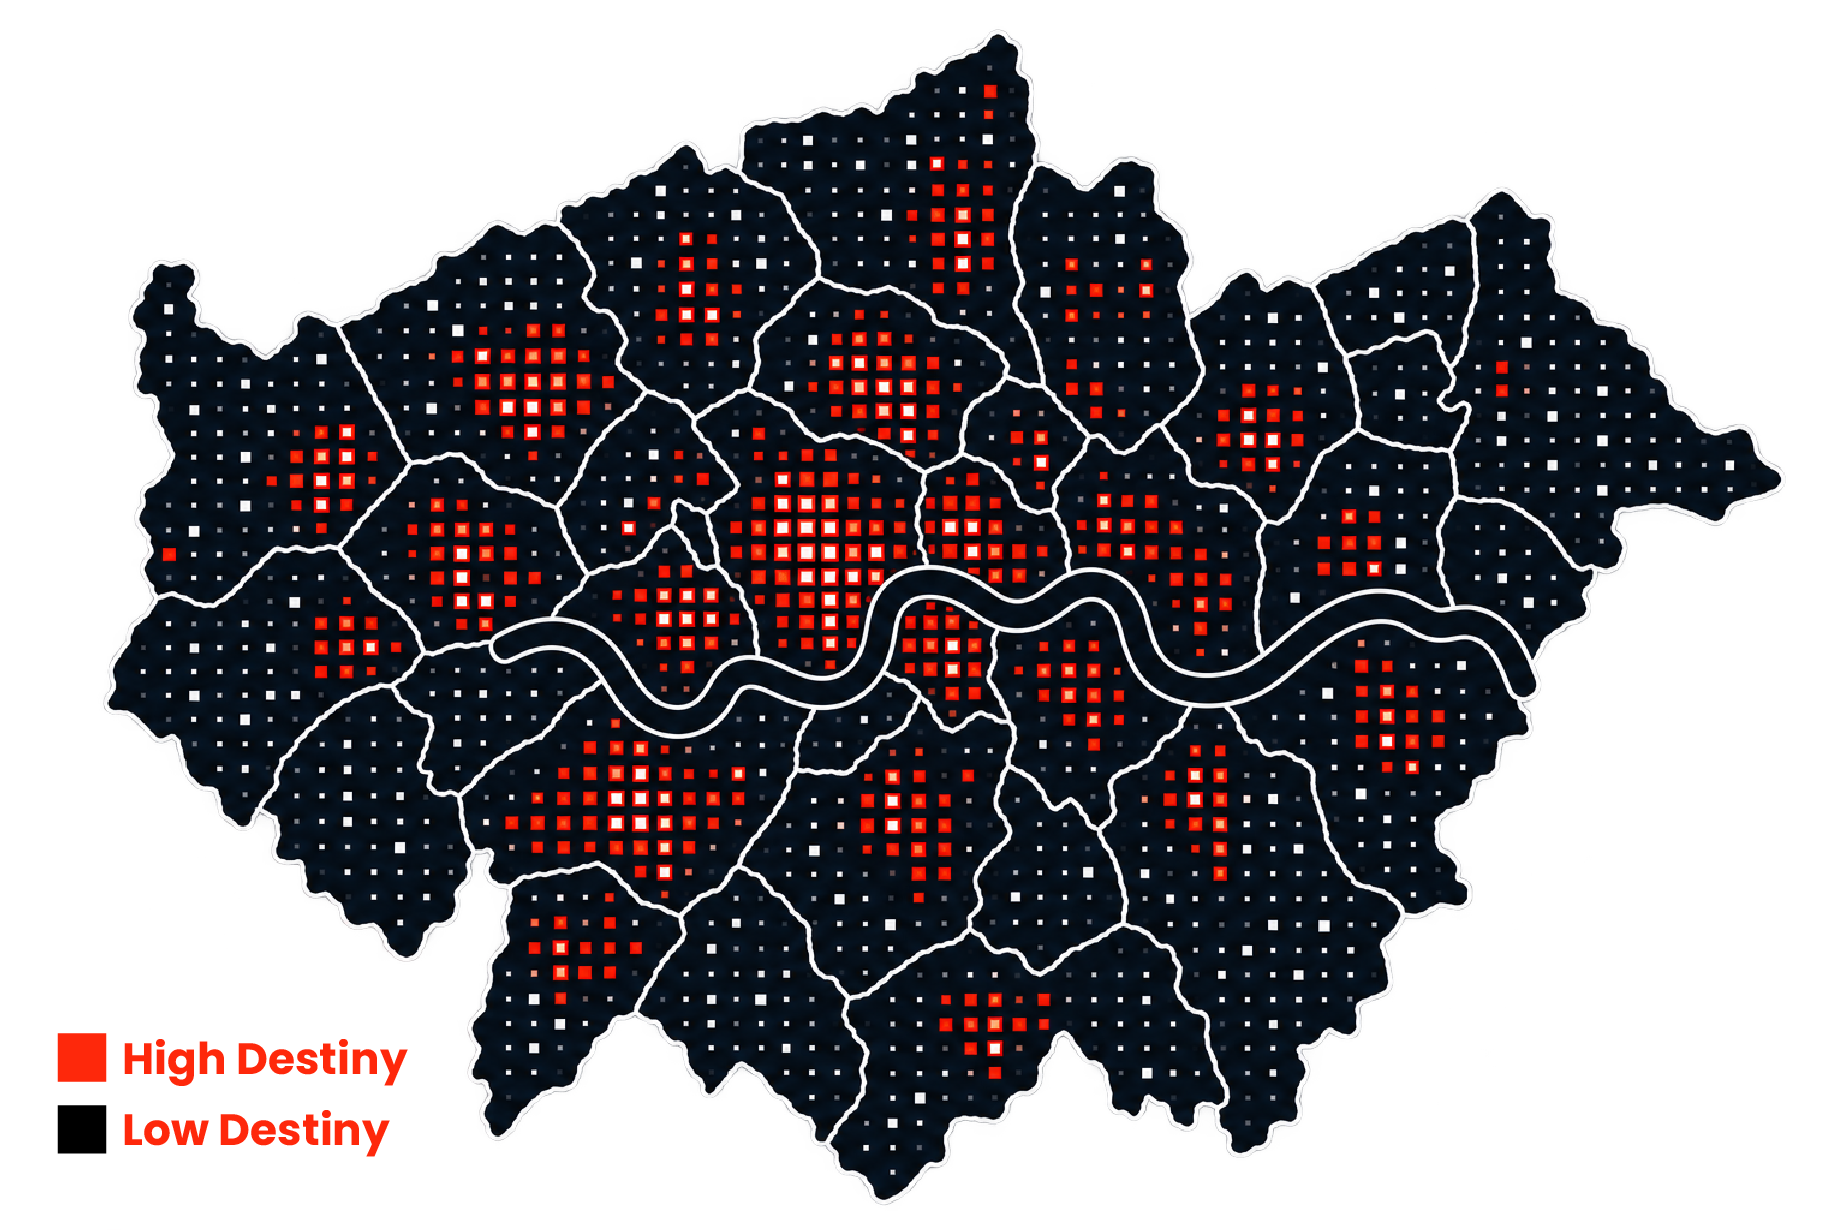
Top London Areas by Hotel Chain Concentration
Districts with the Highest Concentration of Branded Hotel Chains in London
WEST END & MAYFAIR
70+
Driven by luxury tourism, theatres, premium shopping, corporate headquarters, embassies, and high-value international visitors.
KENSINGTON & EARL'S COURT
65+
Supported by museums, leisure tourism, convention activity, residential demand, and access to Heathrow through London's transport network.
PADDINGTON & HYDE PARK
60+
A major accommodation corridor benefiting from Paddington Station, Heathrow connectivity, Hyde Park tourism, and dense hotel development.
CITY OF LONDON & BARBICAN
55+
Strongly influenced by financial services, corporate travel, business events, and weekday demand from professionals.
DOCKLANDS & CANARY WHARF
45+
Corporate offices, financial services, ExCeL London, events, and regeneration projects continue to support hotel demand.
WESTMINSTER & VICTORIA
40+
Government, diplomatic activity, tourism landmarks, rail connectivity, and premium leisure travel create a resilient hotel market.
What is the largest hotel chain in London?
Marriott leads London’s branded hotel ecosystem with 74 Marriott Bonvoy hotels, while Hilton has around 49 properties, including airport locations.
Marriott Hotels & Resorts
HOTELS
Brands
30+
London Areas
25+
Broad portfolio covering luxury, premium, select-service, lifestyle, and extended-stay segments.
Hilton Hotels & Resorts
HOTELS
Brands
15+
London Areas
20+
Large portfolio spanning luxury, full-service, lifestyle, and focused-service accommodation.
Accor
HOTELS
Brands
15+
London Areas
20+
Extensive multi-brand presence ranging from economy and mid-scale to luxury hospitality.
Top 10 Hotel Chains in London by Property Presence and Geographic Distribution – 2026
The table highlights the operational footprint of leading hotel groups and brands across London. Unlike a single-brand comparison, the London market is highly fragmented across global operators, multi-brand portfolios, and individual hotel concepts. Scrape Hotel Chains Location Data provides a structured view of properties, brands, and geographic coverage across this fragmented landscape.
Marriott's official London inventory currently shows 74 hotels, while Radisson states that its Radisson Blu collection alone includes nine London hotels, and Park Plaza lists five London properties. Marriott Hotels & Resorts Hotel Location Dataset can further organize property-level information for location analysis, competitive benchmarking, and hospitality market research.
Accor's London destination page reports more than 45 properties across its brands, reinforcing the scale and diversity of London's hotel market.
| Hotel Chain | Total Properties | Availability (No. of London Areas) | Availability (No. of Locations) | Download Dataset |
|---|---|---|---|---|
| Marriott International | 74+ | 25+ areas | 40+ locations | Download |
| Hilton Hotels & Resorts | 49+ | 20+ areas | 35+ locations | Download |
| Accor | 45+ | 20+ areas | 35+ locations | Download |
| IHG Hotels & Resorts | 40+ | 18+ areas | 30+ locations | Download |
| Radisson Hotel Group | 30+ | 15+ areas | 25+ locations | Download |
| Hyatt | 15+ | 10+ areas | 15+ locations | Download |
| Leonardo Hotels | 15+ | 8+ areas | 12+ locations | Download |
| Best Western | 15+ | 10+ areas | 15+ locations | Download |
| Park Plaza | 5+ | 4+ areas | 5+ locations | Download |
| Premier Inn | Multiple | 15+ areas | 30+ locations | Download |
What are the largest hotel chains in London in 2026?
Location-level hotel data shows that Marriott, Hilton, Accor, IHG, and Radisson have developed broad and diversified London footprints. Their portfolios extend across premium central districts, financial centres, transport hubs, event corridors, and emerging regeneration zones. London Hotel Room Supply Data Extraction helps identify property-level supply patterns and understand how hotel capacity is distributed across different London markets.
Marriott's portfolio includes properties such as London Marriott Hotel County Hall, London Marriott Hotel Grosvenor Square, London Marriott Hotel Kensington, London Marriott Hotel Marble Arch, London Marriott Hotel Park Lane, and JW Marriott Grosvenor House London. Marriott London Hotel chain Intelligence supports comparative analysis of Marriott's geographic coverage, brand presence, and property distribution across the city.
Hilton's London portfolio includes Hilton London Metropole, Hilton London Paddington, London Hilton on Park Lane, Hilton London Canary Wharf, Hilton London Tower Bridge, and multiple Curio Collection properties. Hilton Hotels & Resorts Hotel Location Dataset provides structured location-level information for analysing Hilton's London footprint and competitive positioning.
Accor operates a broad multi-brand portfolio, while IHG's London inventory spans brands including InterContinental, Hotel Indigo, Holiday Inn, Crowne Plaza, and o
Top 10 Hotel Chains in London – 2026
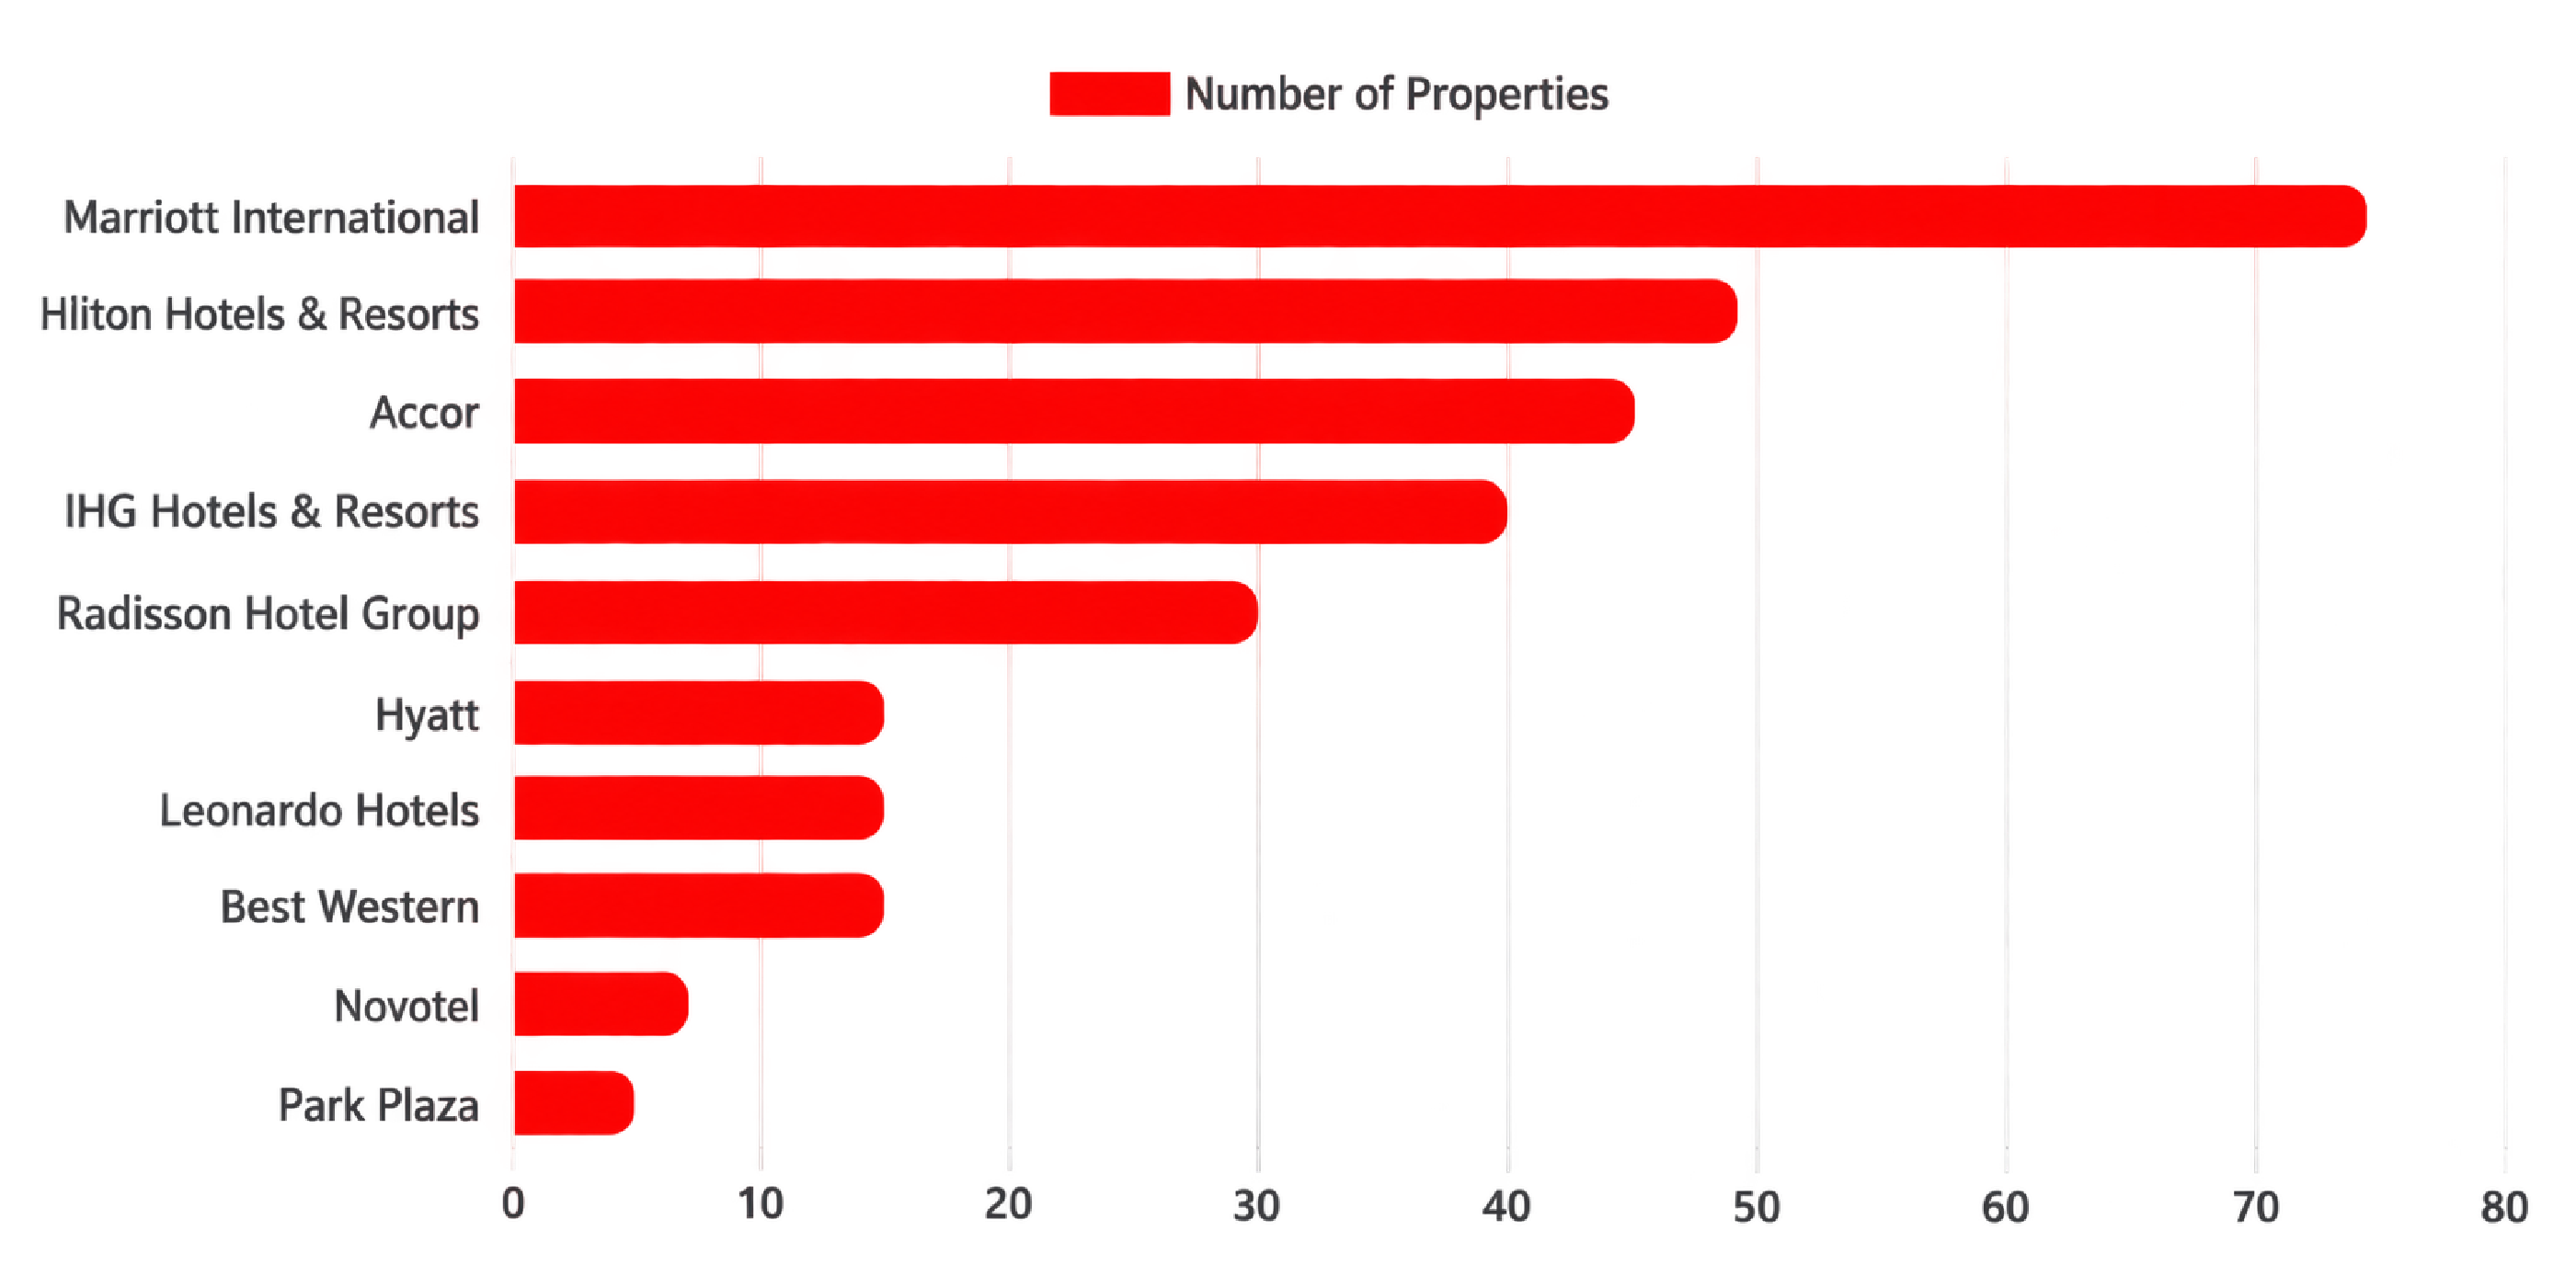
London's hotel landscape is characterized by strong multi-brand competition rather than dominance by one economy operator. Luxury brands concentrate around Mayfair, Park Lane, Knightsbridge, Westminster, and other premium locations, while mid-scale and focused-service brands expand around transport hubs, business districts, and emerging neighborhoods.
Room Type Availability identify exact property addresses, districts, coordinates, brands, hotel categories, room counts, amenities, and opening status. Such datasets allow hospitality analysts to map supply against demand corridors and identify under-served areas.
Hotel Chains Data Scraping also enables continuous monitoring of newly launched properties, rebranded hotels, closures, renovations, and portfolio changes across competitive hotel groups.

Marriott International
Luxury / Premium / Select-ServiceMarriott International is one of London's largest hotel groups, offering luxury, premium, lifestyle, and select-service properties across major business and leisure districts.
Hilton Hotels & Resorts
Luxury / Full-Service / Focused-ServiceHilton operates a substantial London portfolio serving business, leisure, international, and transit travelers across central and airport-connected locations.

Accor
Economy / Mid-Scale / LuxuryAccor maintains a diverse London portfolio spanning economy, mid-scale, premium, lifestyle, and luxury brands across major tourism and business districts.

IHG Hotels & Resorts
Premium / Mid-Scale / LuxuryIHG operates multiple hotel brands across London, serving corporate, leisure, and international travelers while continuing to expand through new developments and conversions.

Radisson Hotel Group
Upper Mid-Scale / PremiumRadisson Hotel Group offers upscale accommodation across central London, business districts, transport corridors, and important commercial destinations.

Hyatt
Luxury / Premium / LifestyleHyatt focuses on premium and luxury hospitality in high-value London locations, targeting corporate travelers, international visitors, and upscale leisure guests.

Leonardo Hotels
Mid-Scale / Upper Mid-ScaleLeonardo Hotels serves business and leisure travelers through strategically positioned properties around London's central business and tourism corridors.

Best Western
Economy / Mid-ScaleBest Western provides affordable and standardized accommodation across London, serving business travelers, tourists, and value-conscious guests.

Park Plaza
Premium / Business / LeisurePark Plaza operates premium hotels in strategic London locations, combining business facilities, leisure amenities, and proximity to major attractions and transport hubs.
Premier Inn
Budget / EconomyPremier Inn maintains a broad London presence focused on affordable accommodation for leisure travelers, business visitors, families, and short-stay guests.
Looking to gain deeper insights into London's hotel chain ecosystem for analytics or investment?
Connect with data specialists for continuously updated hotel locations, room supply, availability, pricing, and competitive intelligence.
Advantages of Chain-Focused Hotel Location Data
Our London hotel chain market analysis datasets provide actionable intelligence for hospitality operators, investors, travel platforms, consultants, property developers, and market researchers.
- Optimizing Chain Performance: Property-level geographic data reveals where brands are over-concentrated, where competitors are expanding, and where underserved demand corridors may exist.
- Enhancing Pricing and Booking Strategies: Continuous hotel monitoring can support rate benchmarking, occupancy analysis, room availability tracking, and demand forecasting.
- Supporting Investment and Expansion Decisions: Investors can compare hotel density, room supply, competitive positioning, transport connectivity, and demand indicators before evaluating potential locations.
- Guiding Regional Market Insights: City and district-level datasets enable analysts to understand differences between Westminster, Mayfair, Kensington, City of London, Canary Wharf, South Bank, Stratford, and other corridors.
- Monitoring New Supply: Tracking openings, renovations, conversions, rebrands, and newly added rooms helps identify changes in competitive capacity before they materially affect market positioning.
| Field Name | Description |
|---|---|
| Hotel Name & Brand | Identifies the property, parent hotel group, and individual brand such as Marriott, Hilton, IHG, Accor, Radisson, or Hyatt. |
| Location Details | Includes borough/district, address, postcode, latitude, longitude, and proximity to important landmarks or transport hubs. |
| Room & Occupancy Data | Captures room counts, room categories, occupancy indicators, booking patterns, and changes in available supply. |
| Pricing & Rate Information | Includes room rates, promotional pricing, seasonal pricing, rate changes, and competitive price movements. |
| Guest Ratings & Reviews | Aggregates review scores, review counts, guest sentiment indicators, and quality benchmarks. |
| Room Type Availability | Tracks available room categories such as Standard, Deluxe, Executive, Twin, Double, Family, and Suites. |
| Opening & Closure Status | Identifies newly opened hotels, planned properties, temporary closures, renovations, and rebranding activity. |
Insights and Analysis
London's hotel market demonstrates the importance of geographic intelligence in understanding competitive supply. Central districts remain highly concentrated, but hotel groups increasingly balance premium central properties with focused-service and business-oriented locations around transport hubs and regeneration zones. Hilton London Hotel Location Dataset can support detailed analysis of property distribution, competitive coverage, and room-supply concentration across London.
The 2025 occupancy performance of 82.5% provides a strong market benchmark heading into 2026, while the London Datastore reported serviced-accommodation occupancy of 81.4% in Q1 2025, illustrating continued but uneven demand across London's sub-regions.
Marriott, Hilton, Accor, IHG, and Radisson illustrate different portfolio strategies. Marriott combines luxury, premium, lifestyle, and select-service concepts; Hilton uses a broad multi-brand portfolio; Accor spans economy through luxury; IHG continues adding differentiated brands; and Radisson maintains strong central positioning. Scrape IHG London New Hotel Rooms Data can help track new openings, room additions, conversions, and changing IHG supply across strategic London locations.
The 2026 IHG Canary Wharf signing is particularly relevant because it demonstrates how established hotel groups continue using conversions and new concepts to access strategically valuable London locations.
Conclusion
As London's hospitality competition intensifies, accurate location and supply intelligence has become essential for understanding expansion opportunities. Structured hotel datasets allow stakeholders to compare brand penetration, room supply, occupancy indicators, pricing, and competitive density across London's major districts.
By using London Hotel Chain Data Scraping, hospitality businesses can continuously monitor changes across Marriott, Hilton, IHG, Accor, Radisson, Hyatt, and other hotel groups. Combining location data with room availability and pricing creates a stronger foundation for investment analysis, site selection, competitive benchmarking, and market-entry planning.
Ultimately, structured London hotel chain datasets can help investors, OTAs, hotel operators, and consultants identify emerging opportunities, evaluate competitive saturation, and make more informed expansion decisions throughout 2026.


