Midscale Hotel Chain Location Data Scraping Europe 2026: ibis vs Premier Inn vs B&B Hotels
This report analyzes Europe's leading midscale hotel chains, their country-wise and city-wise distribution, hotel room supply, occupancy trends, and data-driven expansion opportunities for 2026, comparing ibis, Premier Inn, and B&B HOTELS.
Introduction
Europe remains one of the world's most competitive hospitality markets, supported by international tourism, corporate travel, major events, business districts, cultural attractions, and strong transport connectivity. To understand this evolving market, hospitality companies increasingly Midscale Hotel Chain Location Data Scraping Europe 2026 to monitor hotel openings, closures, brand penetration, room supply, pricing, and geographic expansion.
Europe's branded hotel ecosystem spans economy, midscale, upper-midscale, lifestyle, and extended-stay properties. Hotel directories show extensive distribution across Paris, Berlin, London, Madrid, Rome, Amsterdam, Munich, Barcelona, and other major destinations. Accor reported 1,211 ibis hotels worldwide as of 30 June 2026, while Premier Inn's FY2025/26 reporting recorded 846 hotels in the UK and 65 hotels in Germany. B&B HOTELS lists 939 hotels across 19 countries. These figures represent different geographic scopes and should not be interpreted as directly comparable Europe-only totals. ibis hotel chain location and demand data analytics Europe supports analysis of property distribution, destination coverage, and accommodation demand.
The market is also experiencing continued brand expansion. Premier Inn has developed its German network alongside its established UK business, while B&B HOTELS continues to expand across European countries. Accor's ibis family also provides several distinct brand propositions through ibis, ibis Styles, and ibis budget. Premier Inn hotel chain competitor benchmarking Europe helps compare geographic coverage, property expansion, and competitive positioning across key hospitality markets.
Europe's hotel performance provides an important backdrop for expansion planning. Eurostat reported a 49.9% net occupancy rate for hotel bed places across the European Union in 2025. This is a regional bed-place benchmark rather than a chain-specific room occupancy figure.
400+
Hotel Chain
Properties
Monitored
25+
Major Hotel
Brands
30+
European
Markets & Travel
Corridors Covered
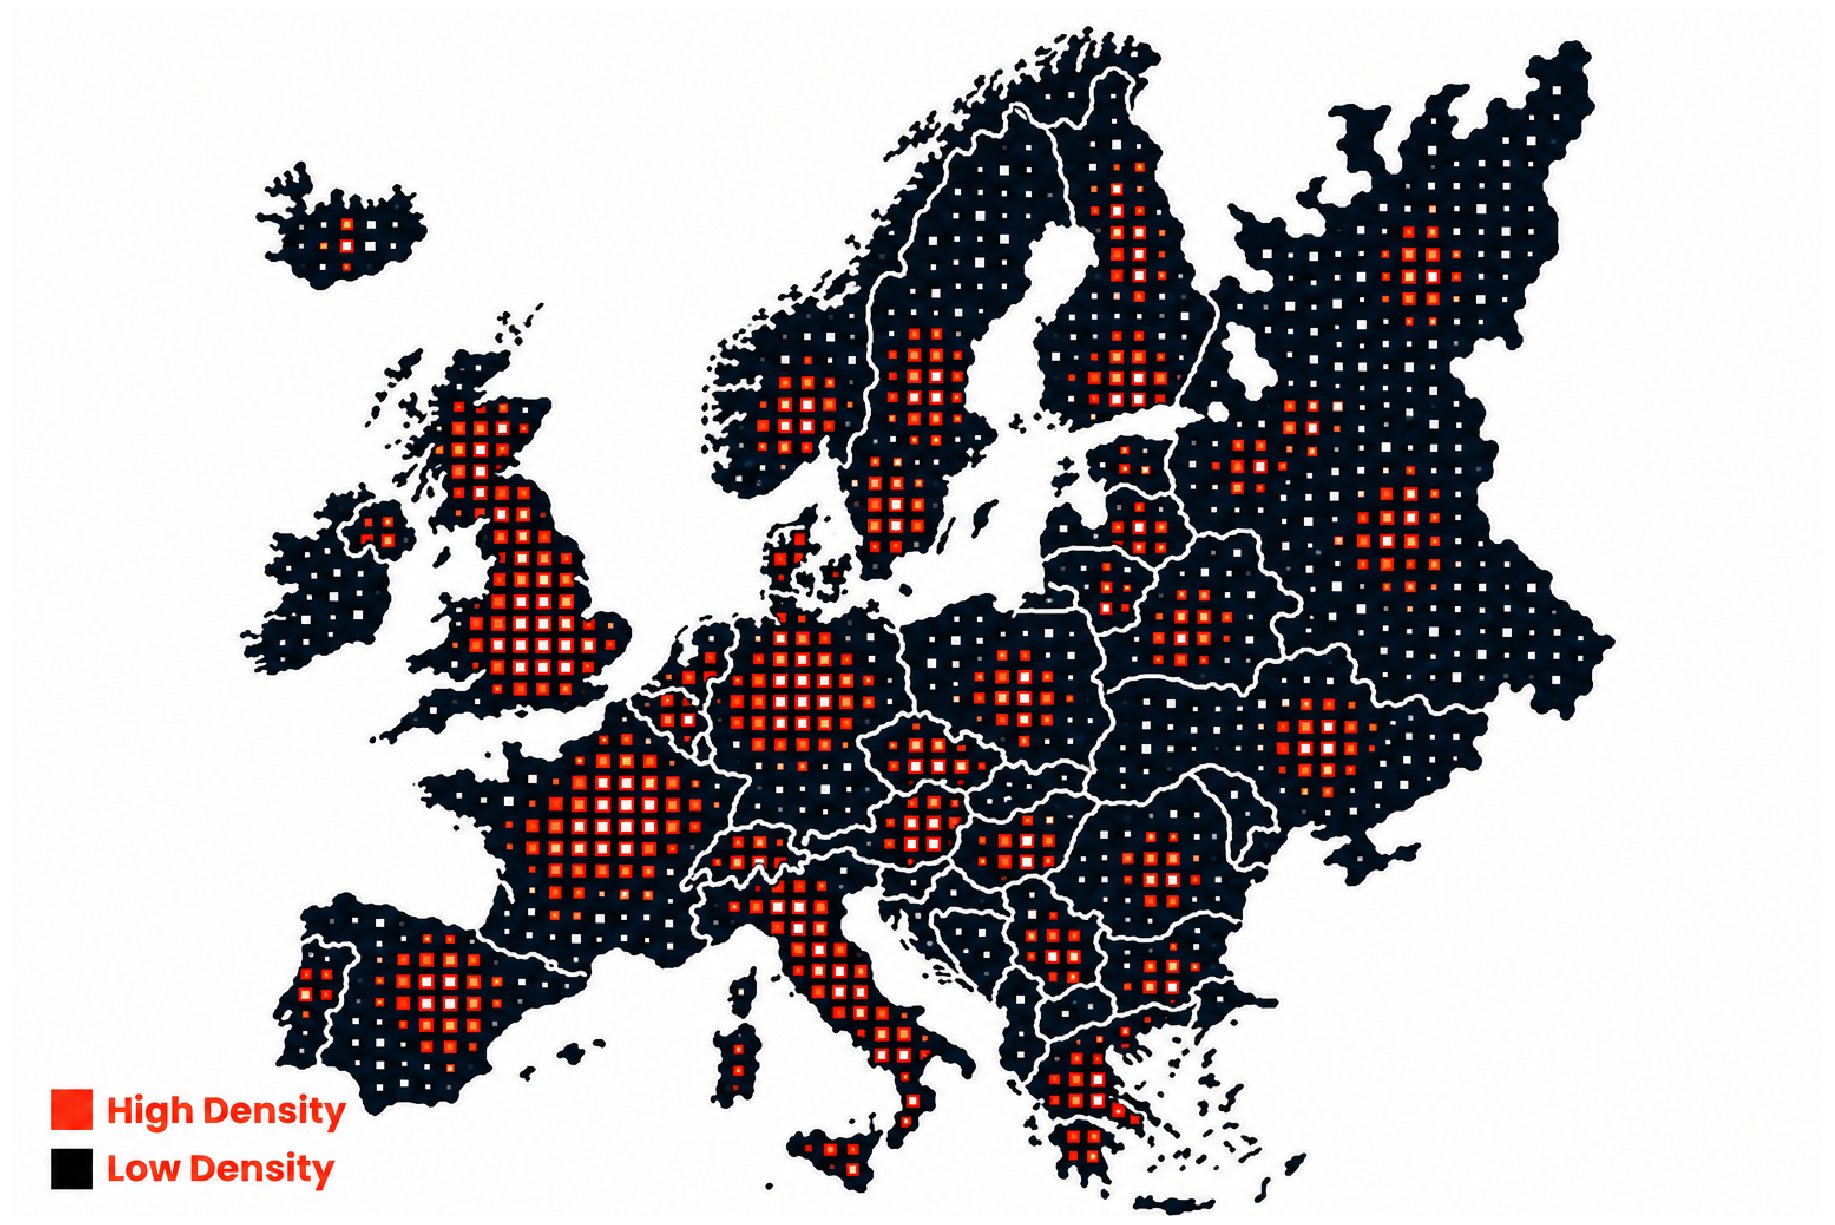
Top European Areas by Midscale Hotel Chain Concentration
Cities with the Highest Concentration of Midscale Hotel Chains Across Europe
PARIS & ÎLE-DE-FRANCE, FRANCE
200+
Driven by international tourism, business travel, airport connectivity, major events, and extensive demand for ibis and B&B HOTELS properties.
LONDON & GREATER LONDON, UNITED KINGDOM
150+
Supported by Premier Inn's extensive UK network, alongside ibis properties, with demand concentrated around business districts, tourist attractions, railway stations, and airports.
BERLIN & BRANDENBURG, GERMANY
100+
A major business and tourism market, supported by ibis and B&B HOTELS properties serving corporate travellers, leisure visitors, exhibitions, and transport corridors.
MADRID & SURROUNDING AREAS, SPAIN
80+
Driven by city tourism, corporate activity, transport connectivity, and demand around commercial districts, convention venues, and airport-access routes.
ROME & LAZIO, ITALY
75+
Supported by international tourism, historic attractions, railway connections, business travel, and accommodation demand around central Rome and surrounding transport hubs.
AMSTERDAM & RANDSTAD, NETHERLANDS
60+
A key hospitality market influenced by international visitors, corporate travel, Schiphol Airport, exhibition activity, and strong transport links.
What is the largest midscale hotel chain in Europe?
ibis, part of Accor, is one of Europe’s leading midscale and economy hotel brands, with a broad international footprint.(kadhi nakho atlu)
ibis
HOTELS
Brands
3
European Markets
Multiple
Core Brands: ibis, ibis Styles, ibis budget. Extensive portfolio spanning economy and midscale accommodation, with properties in major cities, business districts, tourist destinations, and transport corridors.
Premier Inn
HOTELS
Brands
1
European Markets
2
Core Brand: Premier Inn. Large hotel network concentrated in the United Kingdom, with additional operations in Germany and locations serving business and leisure travellers.
B&B HOTELS
HOTELS
Brands
1
European Markets
19
Core Brand: B&B HOTELS. Broad budget and economy hotel network serving city centres, business areas, transport hubs, and regional destinations across Europe.
Top 10 Hotel Chains in Europe by Property Presence and Geographic Distribution – 2026
The table highlights the operational footprint of leading midscale and economy hotel brands across Europe. Unlike a single-market comparison, the European hospitality industry is fragmented across international groups, individual brands, and regional operators. Hotel Chain Location Intelligence provides a structured view of properties, brands, and geographic coverage across this competitive landscape.
Accor's published ibis portfolio provides a global brand benchmark, while Premier Inn's company reporting identifies its UK and German operations separately. B&B HOTELS' corporate directory provides group-wide and country-level references. These records can be standardized for location analysis, competitive benchmarking, and hospitality market research.
| Hotel Chain | Total Properties | Availability (No. of European Markets) | Availability (No. of Locations) | Download Dataset |
|---|---|---|---|---|
| Ibis | 1,211 worldwide | Multiple markets | Europe-only total requires validation | Download |
| Premier Inn | 846 UK + 65 Germany | 2 reported core markets | 911 across UK and Germany | Download |
| B&B HOTELS | 939 group-wide | 19 countries worldwide | Country-level listings available | Download |
| ibis Styles | Separate Accor brand | Multiple markets | Requires brand-level validation | Download |
| ibis budget | Separate Accor brand | Multiple markets | Requires brand-level validation | Download |
| Motel One | Europe-focused portfolio | Multiple markets | Requires current inventory validation | Download |
| Holiday Inn Express | IHG brand | Multiple markets | Europe-only total requires validation | Download |
| Hampton by Hilton | Hilton brand | Multiple markets | Europe-only total requires validation | Download |
| Leonardo Hotels | European portfolio | Multiple markets | Requires current inventory validation | Download |
| Scandic Hotels | Northern European portfolio | Multiple markets | Requires current inventory validation | Download |
Property totals retain their stated reporting scope. "Download" identifies the intended dataset deliverable and is not an active download link.
What are the largest midscale hotel chains in Europe in 2026?
Location-level hotel data shows that ibis, Premier Inn, and B&B HOTELS have developed distinct geographic strategies. Their portfolios extend across capital cities, regional business centres, transport hubs, tourism destinations, and commercial corridors. Europe Midscale Hotel Chain competitor analysis helps identify property-level supply patterns and understand how hotel capacity is distributed across different European markets.
Premier Inn's portfolio includes hotels across London, Manchester, Birmingham, Edinburgh, and other UK destinations, alongside its German network. Premier Inn Hotel Location Dataset supports comparative analysis of its geographic coverage, room supply, and competitive positioning across the UK and Germany.
ibis operates across numerous European destinations through Accor's international network. Its individual hotels can be assessed by country, city, location type, room capacity, and nearby demand centres. Ibis Hotel Location Dataset provides structured location-level information for analysing the ibis footprint and comparing it with competing brands.
B&B HOTELS operates across France, Germany, Italy, Spain, and other countries. B&B Hotels chain property listing data scraping europe helps organize property listings into standardized records for identifying geographic concentrations, tracking new locations, and evaluating competitive coverage.
Top 10 Hotel Chains in Europe – 2026
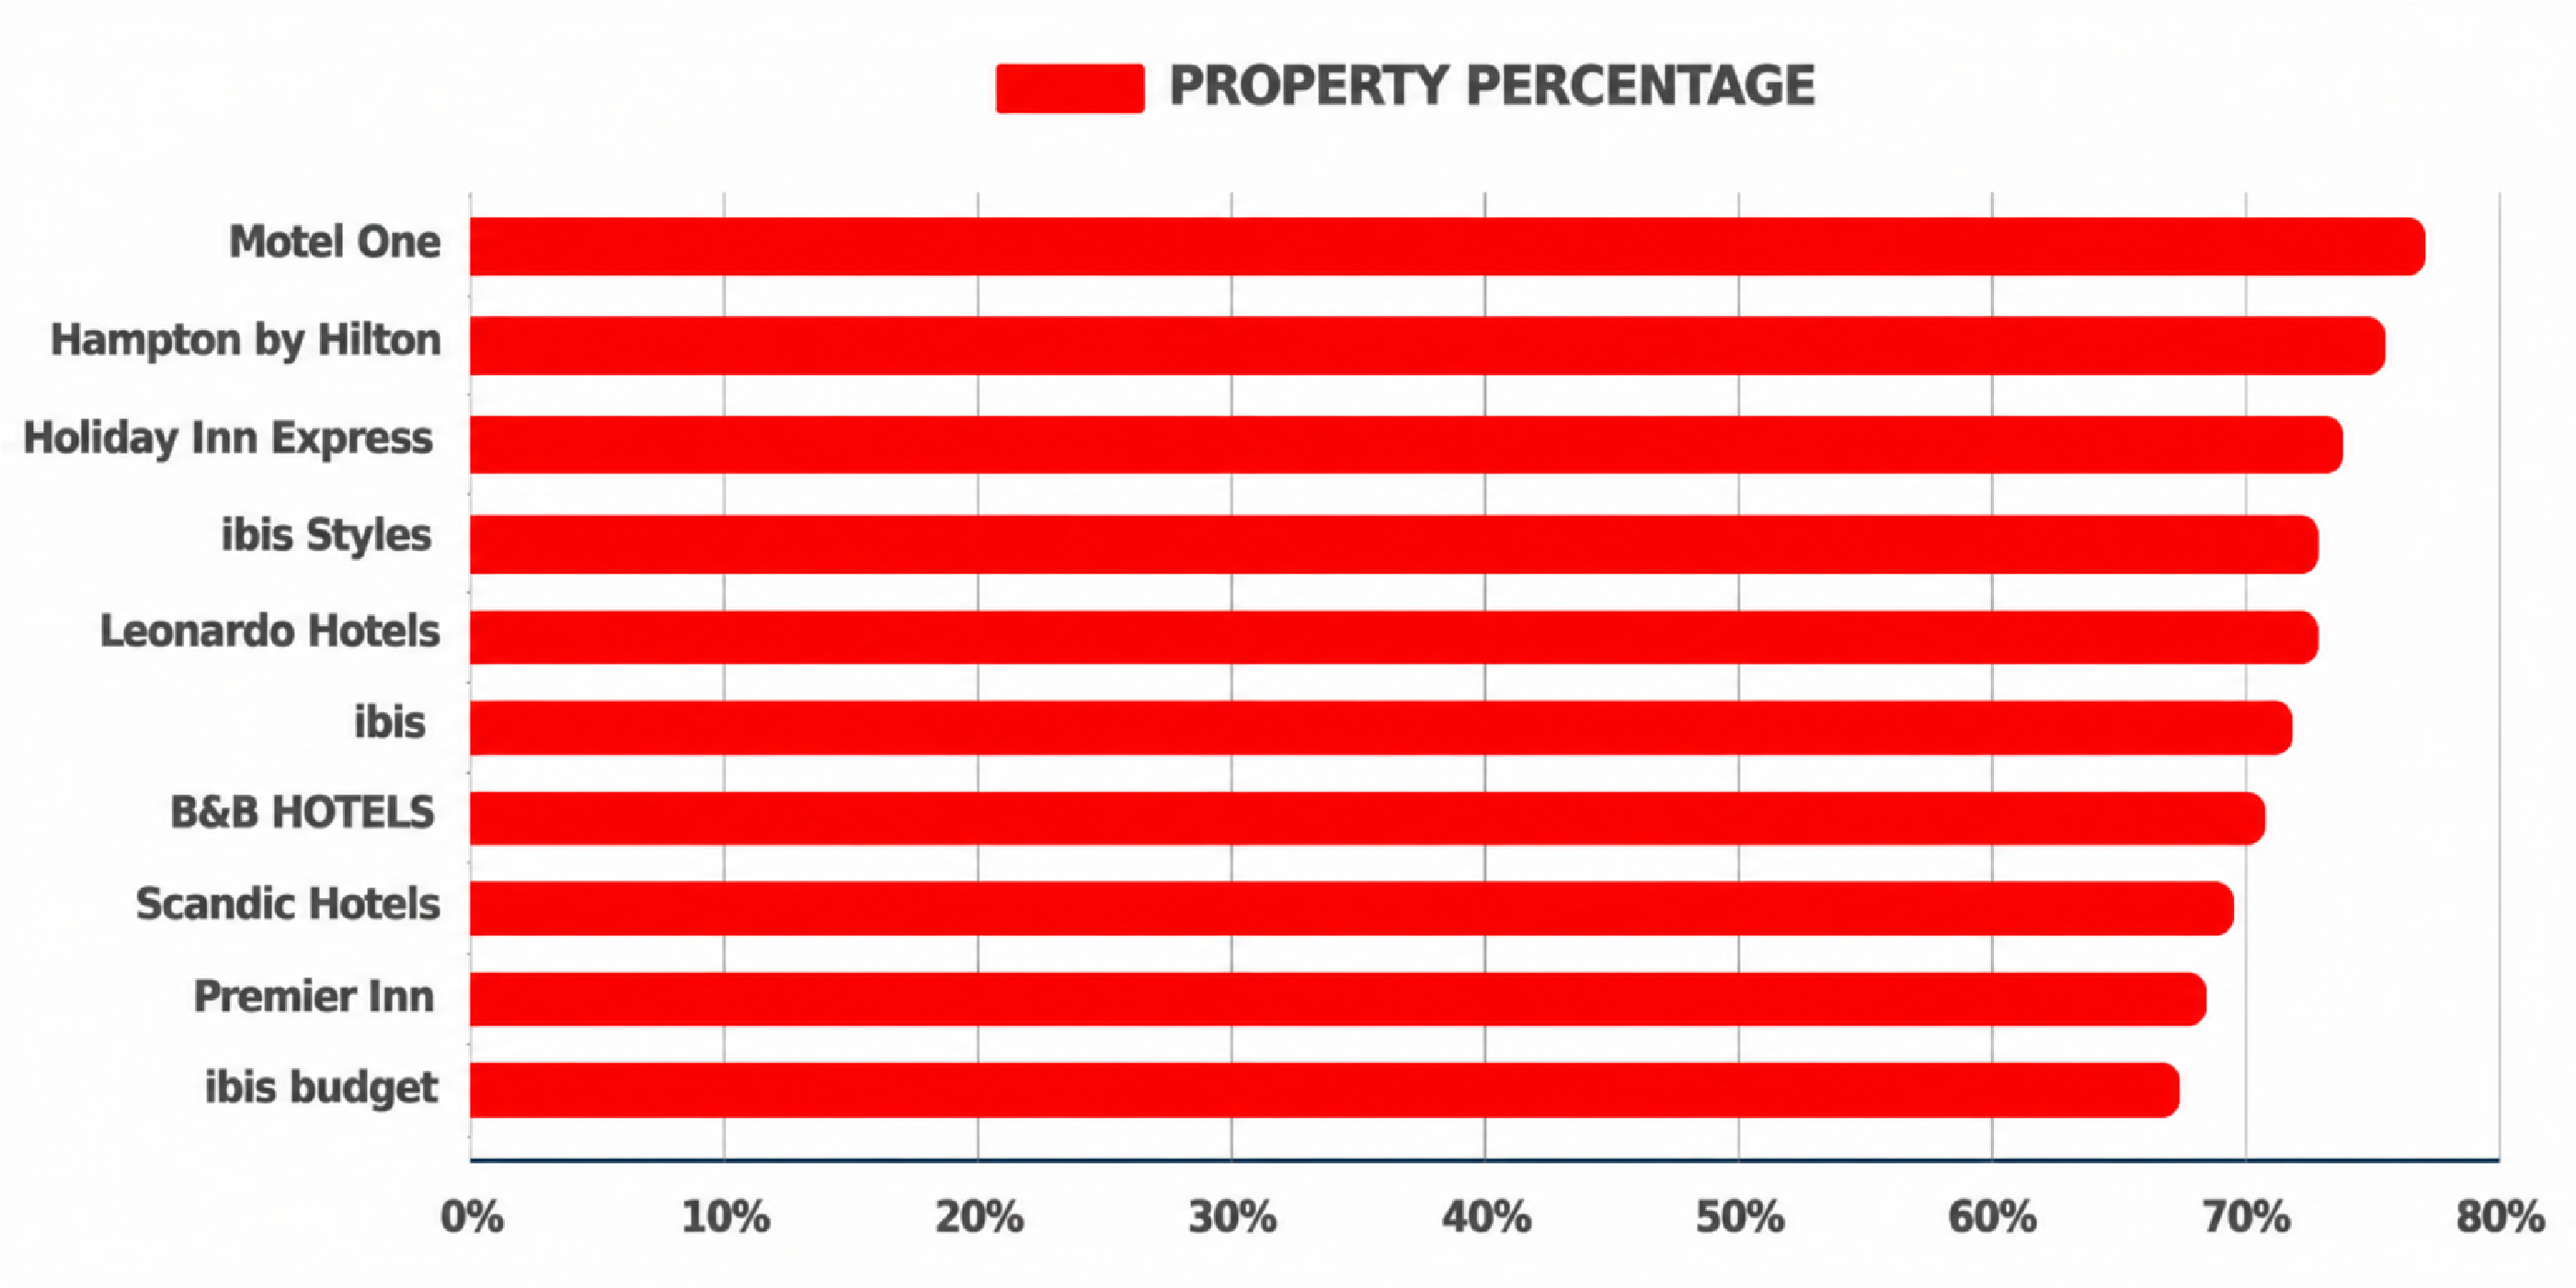
Europe's midscale and economy hotel landscape is characterized by competition among international brands, value-focused operators, and regional hotel groups. ibis benefits from Accor's global distribution, Premier Inn has an established UK network, and B&B HOTELS has built a broad presence across European markets.
Property location data helps identify where these brands overlap around city centres, railway stations, airports, business districts, and tourism destinations. scrape midscale hotel chain locations across Europe to identify exact property addresses, districts, coordinates, room counts, amenities, hotel categories, and opening status. Such datasets allow hospitality analysts to map supply against demand corridors and identify potentially underserved areas.
Hotel Chains Data Scraping also enables continuous monitoring of newly launched properties, rebranded hotels, closures, renovations, and portfolio changes across competitive hotel groups.

ibis
Economy / Value-Focusedibis is one of Accor's established economy brands, offering standardized accommodation across European business and leisure destinations.
Europe-wide inventory requires validation

Premier Inn
Value-Focused / MidscalePremier Inn operates a substantial hotel network in the UK and a growing German portfolio, serving business travelers, tourists, families, and short-stay guests.
UK Core Market

B&B HOTELS
Economy / Value-FocusedB&B HOTELS maintains a broad European presence, serving business and leisure travelers through standardized accommodation and a multi-country expansion strategy.
Multi-country presence
ibis Styles
Economy / Lifestyleibis Styles offers a design-oriented hotel experience within Accor's ibis family, providing a separate brand category for competitive analysis.
Brand-level count requires validation

ibis budget
Economy / Budgetibis budget targets price-conscious travelers through essential accommodation in urban, suburban, and transport-linked locations.
Brand-level count requires validation

Motel One
Economy / Design-LedMotel One combines design-led accommodation with urban locations, making it a relevant competitor in European city markets.
Current inventory requires validation

Holiday Inn Express
Economy / Focused-ServiceHoliday Inn Express serves business and leisure travelers through standardized accommodation across multiple European markets.
Europe-only count requires validation

Hampton by Hilton
Economy / Focused-ServiceHampton by Hilton competes in the focused-service segment with standardized rooms and a broad international distribution network.
Europe-only count requires validation

Leonardo Hotels
Midscale / Upper MidscaleLeonardo Hotels serves corporate and leisure travelers through properties across European cities and regional commercial destinations.
Current inventory requires validation

Scandic Hotels
Midscale / Upper MidscaleScandic maintains a strong Northern European presence, serving business and leisure travelers across Nordic capitals and regional markets.
Current inventory requires validation
Looking to gain deeper insights into Europe's midscale hotel chain ecosystem for analytics or investment?
Connect with data specialists for continuously updated hotel locations, room supply, availability, pricing, and competitive intelligence across European markets.
Advantages of Chain-Focused Hotel Location Data
Our Europe midscale hotel chain market analysis datasets provide actionable intelligence for hospitality operators, investors, travel platforms, consultants, property developers, and market researchers.
- Optimizing Chain Performance: Property-level geographic data reveals where brands are concentrated, where competitors are expanding, and where underserved business and leisure travel corridors may exist.
- Enhancing Pricing and Booking Strategies: Continuous hotel monitoring can support rate benchmarking, occupancy analysis, room availability tracking, seasonal comparisons, and demand forecasting across European destinations.
- Supporting Investment and Expansion Decisions: Investors can compare hotel density, room supply, competitive positioning, transport connectivity, and demand indicators before evaluating potential locations.
- Guiding Regional Market Insights: City and country-level datasets enable analysts to understand differences between Paris, Berlin, London, Madrid, Rome, Amsterdam, and other European markets.
- Monitoring New Supply: Tracking openings, renovations, conversions, rebrands, and newly added rooms helps identify changes in competitive capacity before they materially affect market positioning.
| Field Name | Description |
|---|---|
| Hotel Name & Brand | Identifies the property, parent hotel group, and individual brand such as ibis, Premier Inn, B&B HOTELS, and other competing operators. |
| Location Details | Includes country, city, district, address, postcode, latitude, longitude, and proximity to important landmarks or transport hubs. |
| Room & Occupancy Data | Captures room counts, room categories, occupancy indicators, booking patterns, and changes in available supply where disclosed. |
| Pricing & Rate Information | Includes room rates, promotional pricing, seasonal pricing, rate changes, and competitive price movements. |
| Guest Ratings & Reviews | Aggregates review scores, review counts, guest sentiment indicators, and quality benchmarks. |
| Room Type Availability | Tracks available room categories such as Standard, Deluxe, Twin, Double, Family, and Suites where listed. |
| Opening & Closure Status | Identifies newly opened hotels, planned properties, temporary closures, renovations, and rebranding activity. |
Insights and Analysis
Europe's midscale hotel market demonstrates the importance of geographic intelligence in understanding competitive supply. Major cities remain important accommodation markets, while hotel groups balance established urban locations with business-oriented properties, transport corridors, and regional destinations. Europe Midscale hotel chain location data for market analysis can support detailed analysis of property distribution, competitive coverage, and room-supply concentration across Europe.
The European Union's 2025 net occupancy rate of 49.9% for hotel bed places provides a regional reference for understanding accommodation demand. However, occupancy varies by destination, season, and property type, so chain-specific analysis requires comparable local indicators rather than applying a single European average to every hotel.
ibis, Premier Inn, and B&B HOTELS illustrate different portfolio strategies. ibis benefits from international brand recognition and Accor's distribution network; Premier Inn combines a substantial UK estate with its German operation; and B&B HOTELS maintains a multi-country European presence. These differences make consistent property-level data valuable for comparing competitive coverage and identifying potential expansion markets.
The German market provides a useful example. Premier Inn reported 65 hotels and 11,598 rooms in Germany for FY2025/26, alongside an occupancy rate of 69.0%. Comparable analysis of competing properties can help determine how room capacity, location, and pricing relate to performance across similar destinations.
Reliable data collection should distinguish open properties from announced developments, preserve separate records for individual brands, and record the date and source of changing information. Hotel Chain Location Intelligence can combine these standardized records with pricing, availability, and demand indicators to help businesses evaluate hotel supply and monitor competitive developments throughout 2026.
Conclusion
As Europe's hospitality competition intensifies, accurate location and supply intelligence has become essential for understanding expansion opportunities. Structured hotel datasets allow stakeholders to compare brand penetration, room supply, occupancy indicators, pricing, and competitive density across European markets.
By using location data alongside room availability and pricing, hospitality businesses can continuously monitor changes across ibis, Premier Inn, B&B HOTELS, and other hotel groups. Combining verified property information with market indicators creates a stronger foundation for investment analysis, site selection, competitive benchmarking, and market-entry planning.
Ultimately, structured hotel chain datasets supported by Hotel Data Intelligence can help investors, OTAs, hotel operators, and consultants identify emerging opportunities, evaluate competitive saturation, and make more informed expansion decisions throughout 2026.


